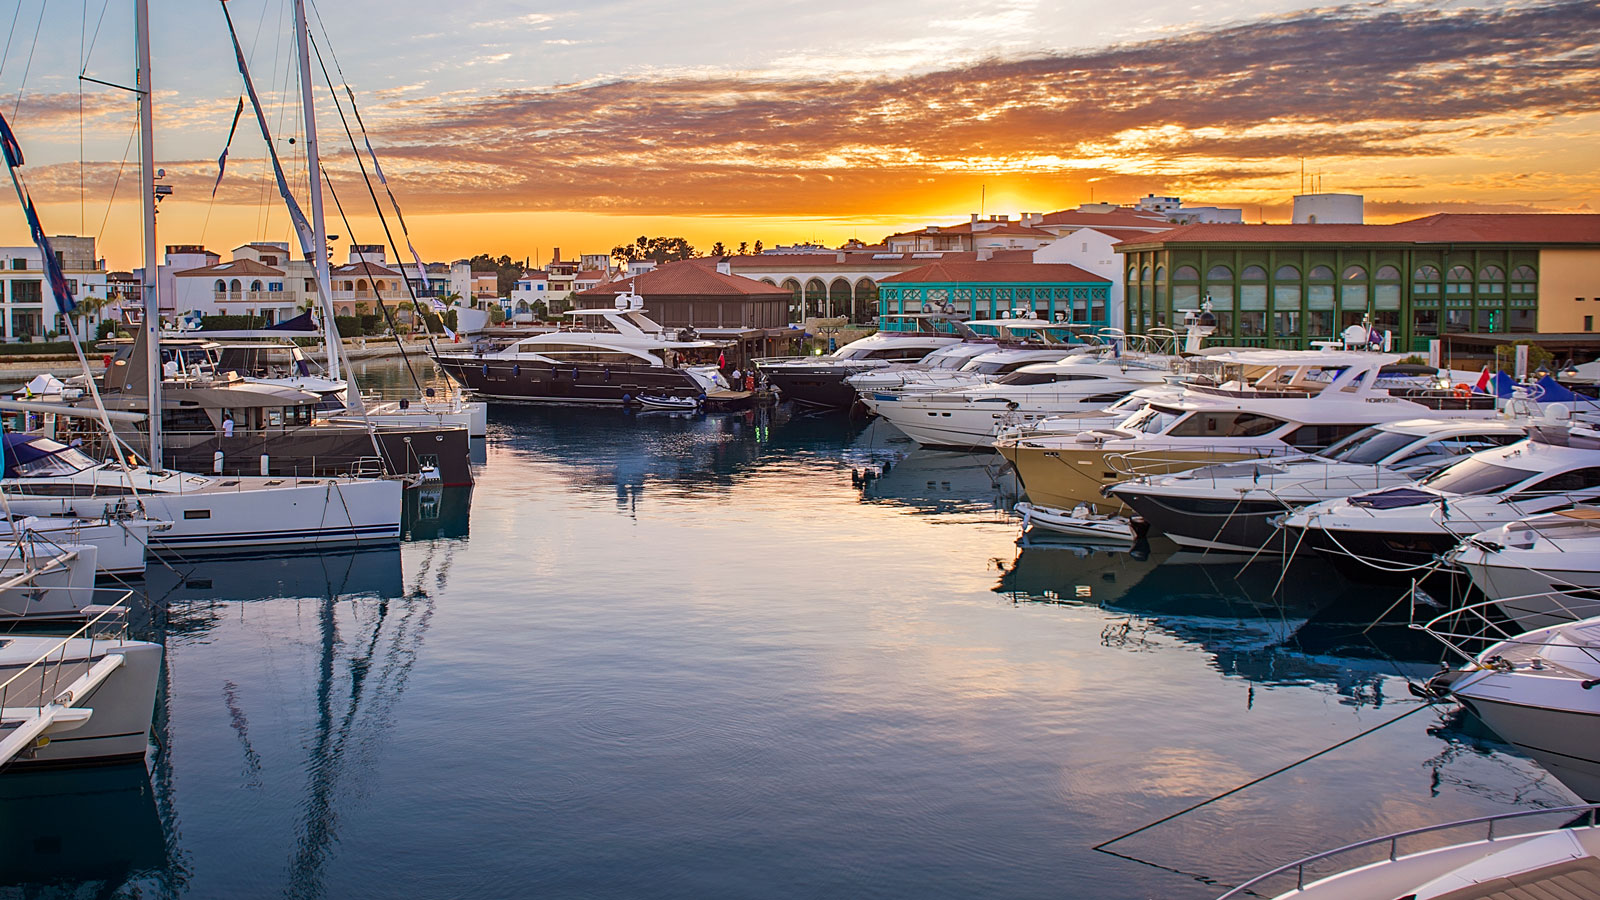
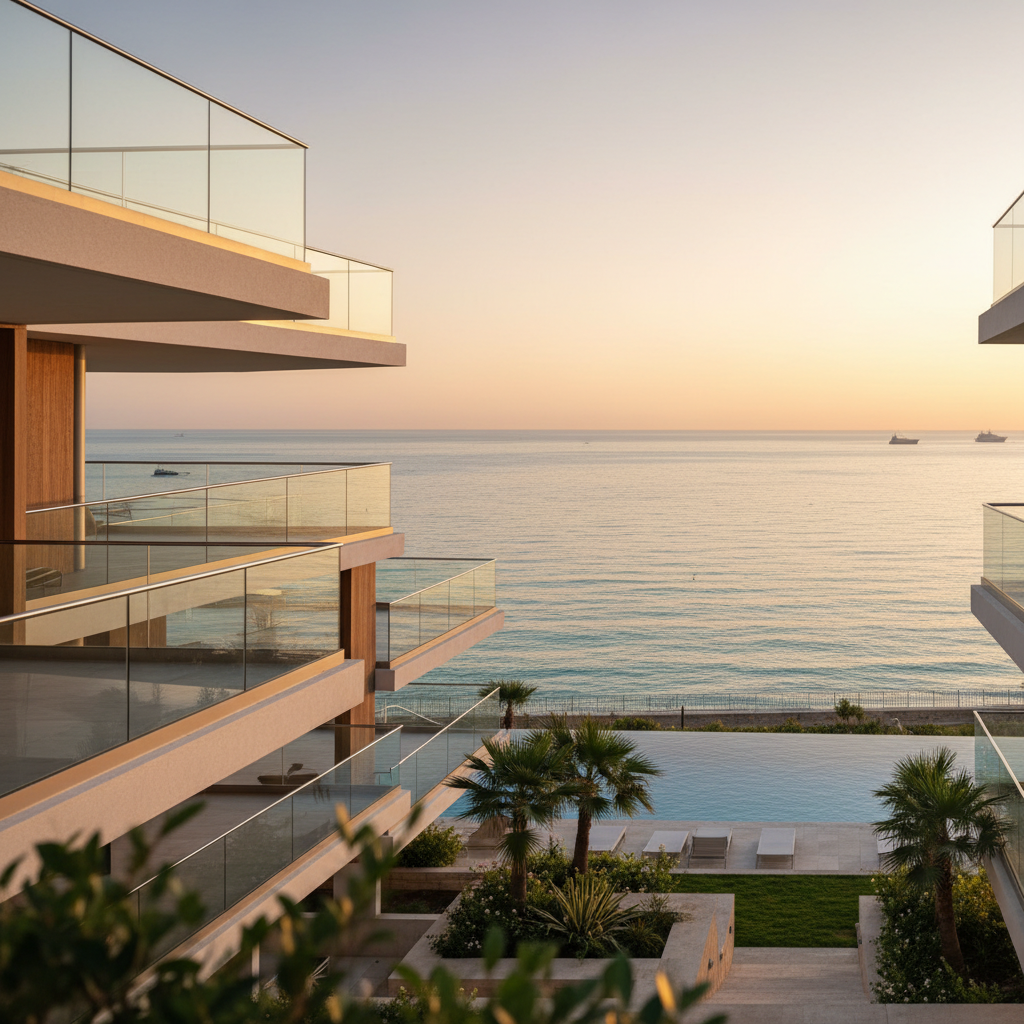
Limassol's coastal ribbon has long served as the definitive barometer for the broader island property landscape. Recent high-end residential releases demonstrate a decisive recalibration, moving past speculative momentum toward sustained, quality-driven benchmarks. For discerning international capital, analysing the initial pricing phases of these new schemes provides an unclouded view of where real asset values are consolidating across the Mediterranean.
Decoding the Shift in Coastal Square-Metre Valuations
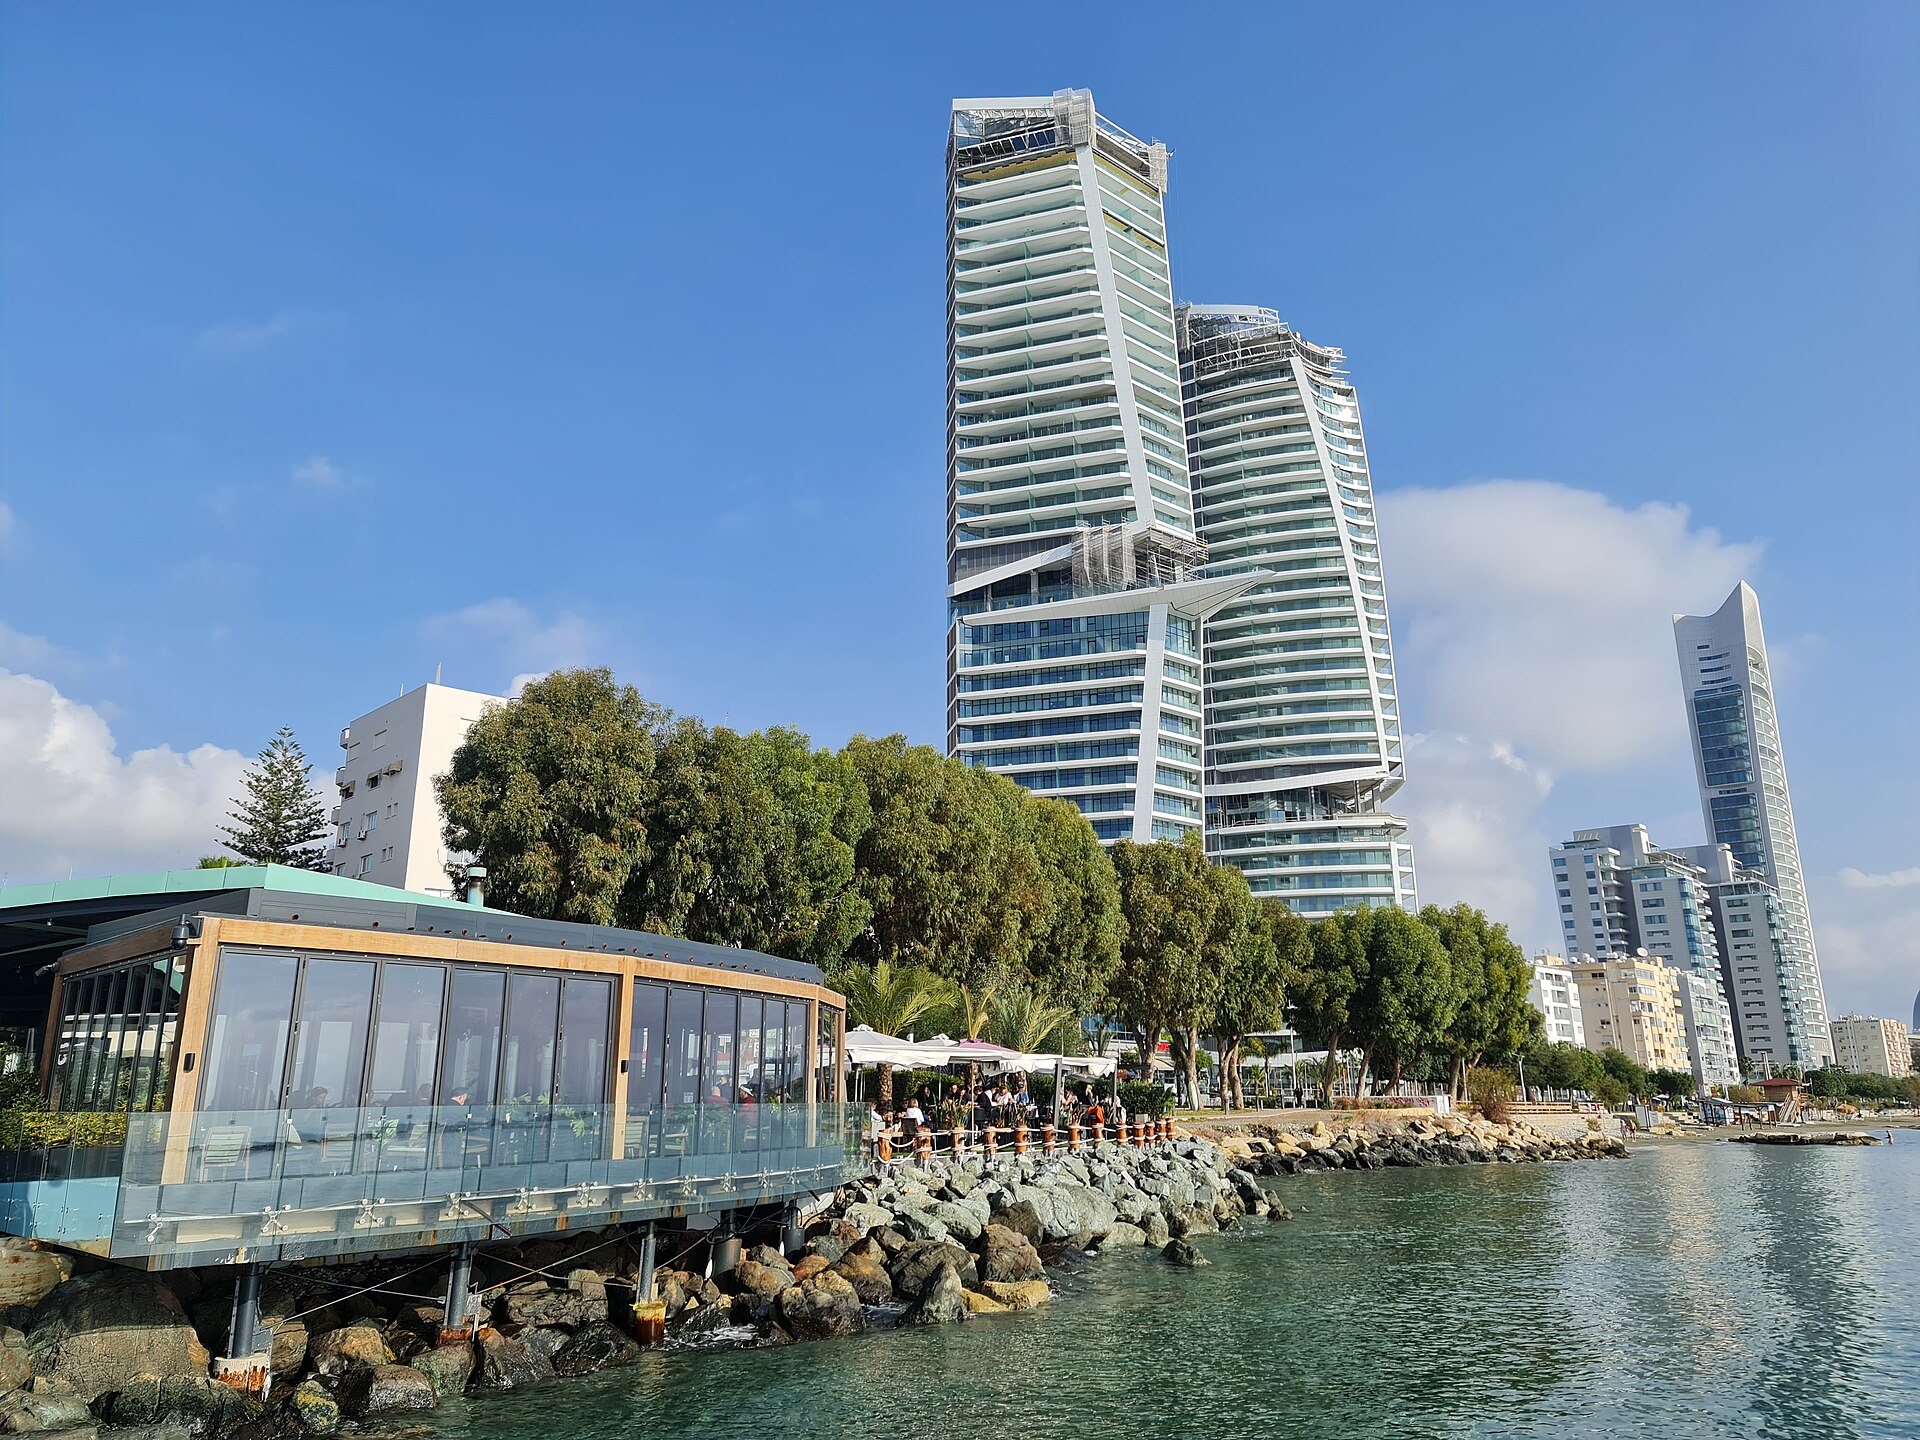
The latest generation of seafront apartments Cyprus is welcoming reveals a notable divergence between pure height and architectural merit. While the previous development cycle frequently prioritised sheer elevation along the coastline, current launches emphasise lower-density luxury, bespoke finishes, and integrated residential amenities. This evolution has anchored baseline asking rates at a higher floor, with off-plan premiums no longer reflecting inflationary pressure, but rather tangible structural craftsmanship and genuine scarcity of prime shoreline plots.
"The current pricing structure along the coastline reflects not speculative optimism, but an international institutional re-rating of prime Mediterranean land."
Comparative Dynamics Across the Island
While Limassol real estate continues to command the highest tier of island pricing, ripple effects are altering investor calculus in secondary hubs. Capital evaluating the coastal strip is increasingly measuring gross yields against emerging waterfront opportunities in Larnaca and the marina quarters of Ayia Napa. Concurrently, prime villas in Paphos and established corporate addresses in Nicosia provide distinct risk-adjusted profiles, yet none duplicate the liquidity and foreign direct investment volume concentrated along Limassol’s shoreline.
Key Takeaways for High-Net-Worth Acquisitions
- Contract structures increasingly tie phase pricing to rigorous construction milestones rather than speculative calendar targets.
- Secondary market resales in early-generation towers face pricing pressure when competing against newly engineered thermal and acoustic specifications.
- Buyer profiles have shifted permanently toward long-term family offices and technology executives establishing regional headquarters.
- Micro-location within Limassol—specifically proximity to the historical core versus eastern coastal stretches—now dictates capital appreciation trajectories.
Practical Considerations and Forward Outlook
Entering the prime Limassol seafront market requires a forensic examination of underlying land tenure, developer balance sheets, and operational management contracts. With service charges reflecting private concierges, wellness clubs, and sea-facing grounds, calculating net yields demands clarity on ongoing operational expenditures. As building permits become tighter under updated municipal planning frameworks, existing unbuilt beachfront land will inevitably command unprecedented premiums.
Looking ahead, the coastal trajectory suggests a stable plateau rather than unchecked vertical spikes, creating an advantageous window for deliberate portfolio deployment. Rather than chasing short-term arbitrage, institutional and private capital is securing generational assets with enduring sea horizons. For those observing the Mediterranean prime sector, Limassol's current baseline represents a matured European asset class capable of withstanding broader macroeconomic headwinds.