Over the past decade, international tax architecture has undergone significant consolidation. As jurisdictions across Europe dismantle legacy remittance regimes and increase regulatory scrutiny, high-net-worth families are systematically reassessing where they hold residency. Within this shifting landscape, Cyprus has emerged not merely as a transitional refuge, but as one of the European Union's most stable, predictable, and structurally advantageous jurisdictions for internationally mobile wealth.
The Architecture of Cyprus Non-Dom Status
Introduced in 2015 to attract foreign capital and senior executives, the Cyprus non-dom regime provides a comprehensive exemption from the Special Defence Contribution (SDC) tax for up to seventeen years. Under standard domestic law, Cyprus tax residents are subject to SDC on passive income streams. However, an individual who qualifies as non-domiciled is entirely exempt from domestic taxation on global dividends, passive interest income, and gains arising from the disposal of shares and securities.
Crucially, domicile in Cyprus is determined by either origin or choice. Foreign nationals relocating to the island are categorised as having a domicile of origin outside Cyprus, meaning they can access the full breadth of the regime immediately upon establishing residency. With no inheritance tax, zero wealth tax, and an extensive network of double taxation treaties, Cyprus non-dom status establishes a robust European platform for family offices and cross-border enterprise.
The 60-Day Rule: Pragmatism for Global Principals
Historically, establishing tax residency Cyprus required a physical presence of at least 183 days per calendar year. Recognizing that modern executives, fund managers, and entrepreneurs maintain global operational commitments, the government established the 60-day tax residency rule. This legislative mechanism offers unmatched mobility without compromising sovereign fiscal validity.
- Reside in Cyprus for at least 60 cumulative days within the relevant assessment year.
- Refrain from residing in any other single country for a period exceeding 183 days.
- Ensure you are not deemed a tax resident under the domestic laws of any third state.
- Maintain an active business engagement, executive office, or registered corporate directorship in Cyprus.
- Retain a permanent residential property on the island, held either via freehold ownership or long-term lease.
Aligning Property Acquisition with Relocation Realities
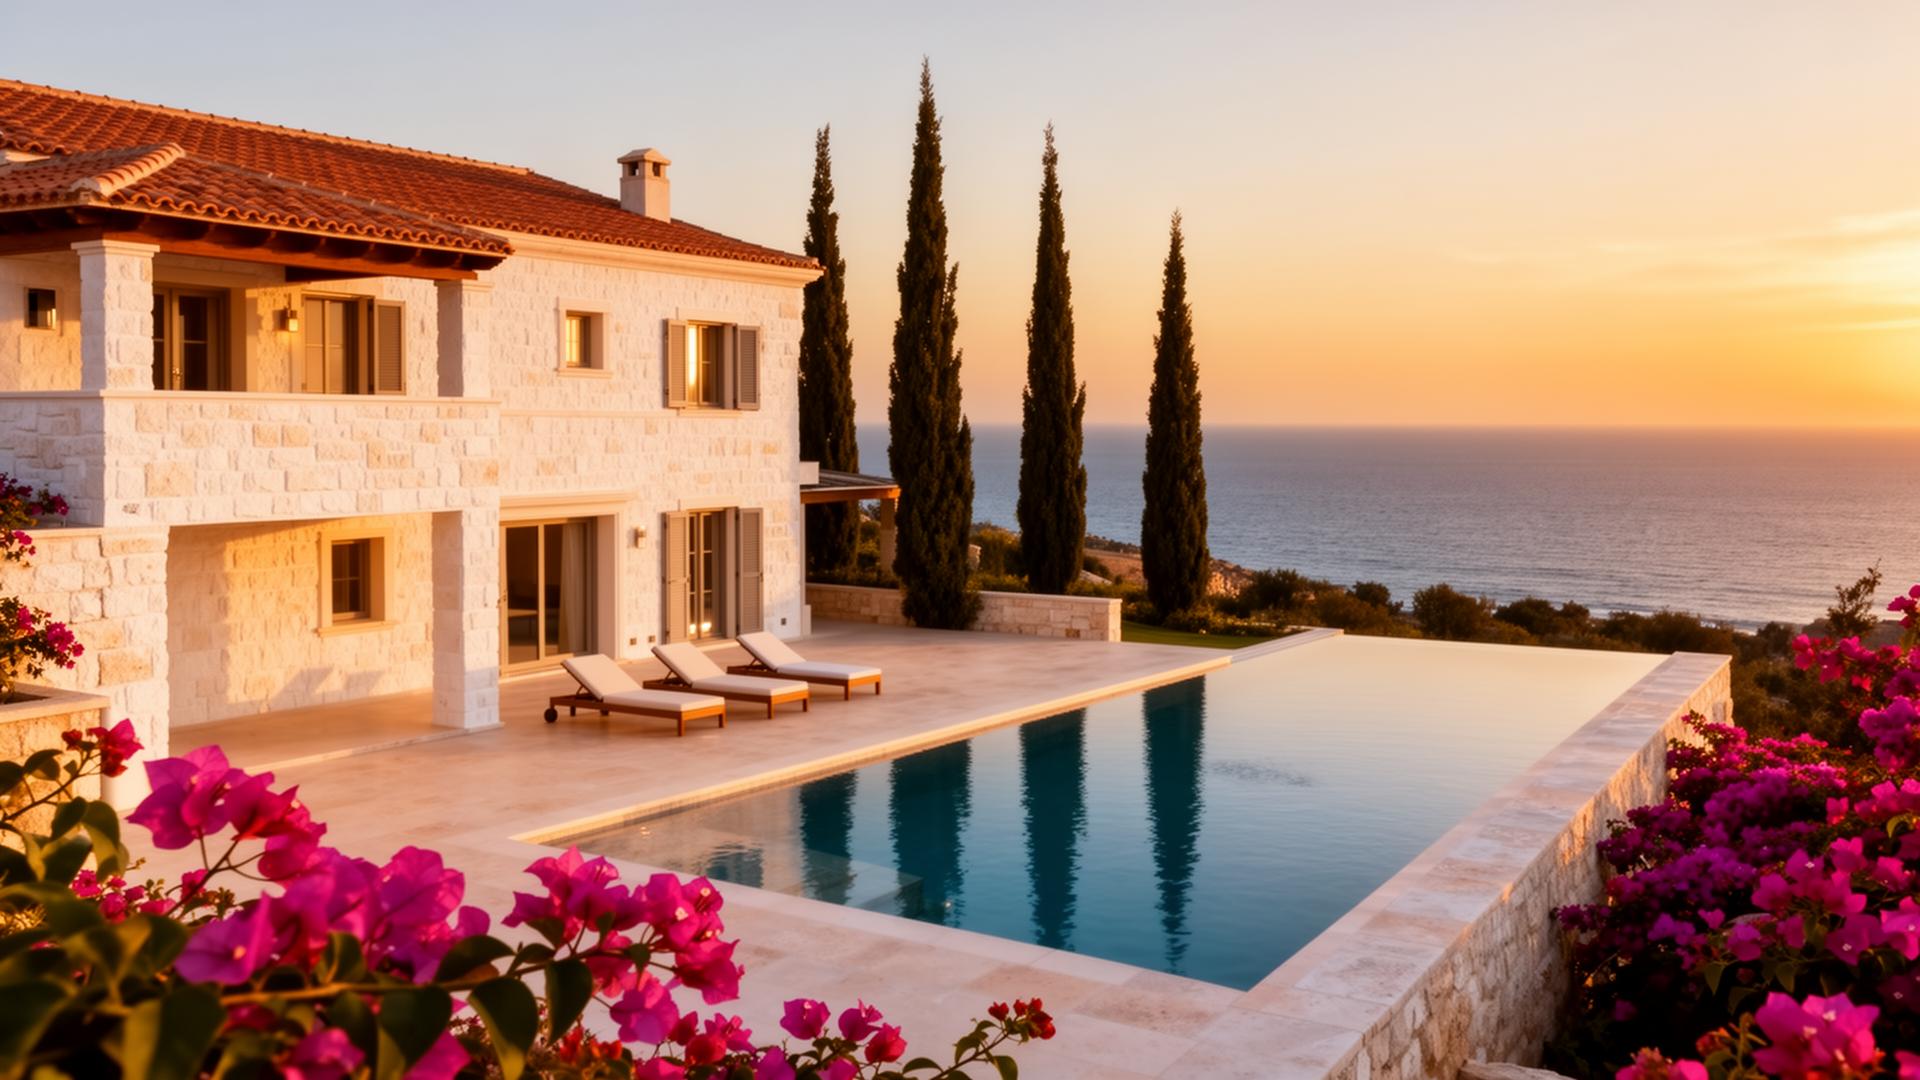
Fulfilling the residential property mandate should be approached as both a compliance milestone and an enduring lifestyle asset. In Limassol, international families gravitate toward contemporary coastal villas and serviced high-rises along the eastern seafront, where proximity to private English-medium schools and international corporate services provides immediate convenience. For those whose focus centres on capital stability and diplomatic connectivity, Nicosia presents stately private residences within established residential enclaves.
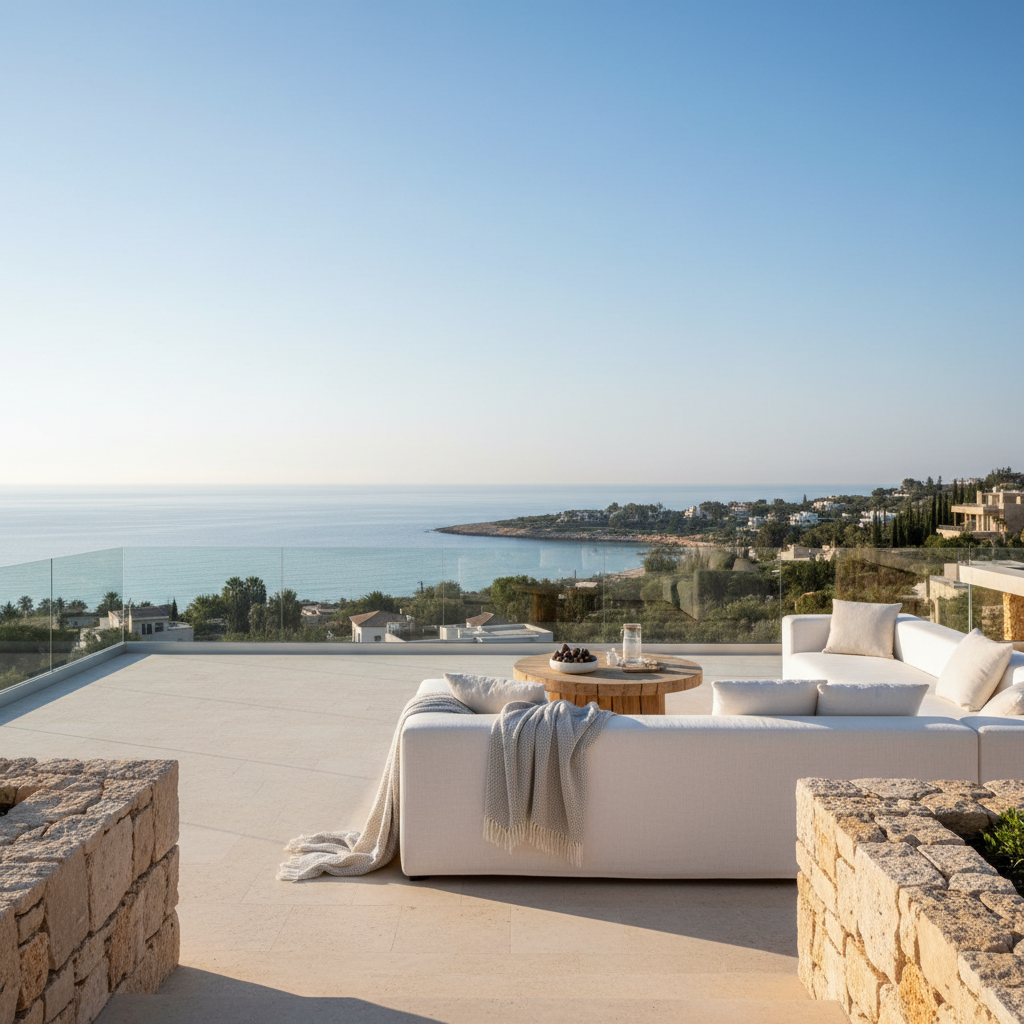
Conversely, buyers seeking privacy, generous land plots, and sea views increasingly favour Paphos and the surrounding hills, where master-planned golf resorts and coastal retreats cater to multi-generational living. Those prioritizing direct maritime access and rapid transit to international business routes look toward Larnaca, where waterfront redevelopment and proximity to the main international airport deliver seamless regional transit.
"Cyprus does not merely offer fiscal optimisation; it combines the legal certainty of an EU member state with an exceptional quality of daily life."
Executing the Relocation: Practical Milestones
A successful relocation requires disciplined chronological execution. The transition commences with immigration clearance, which for third-country nationals typically entails an expedited permanent residency application linked to a primary real estate investment of at least €300,000. Concurrently, personal and corporate accounts must be established with tier-one domestic and international private banking institutions operating across Nicosia and Limassol.
Following physical property completion or lease commencement, individuals register with the Civil Registry and Migration Department to secure the initial registration certificate, followed by registration with the Cyprus Tax Department for the issuance of a Tax Identification Code. Non-dom application affidavits are subsequently filed through local counsel, certifying non-domiciled status and formalising the seventeen-year exemption.
As fiscal landscapes in traditional centres continue to tighten, the viability of arbitrary regimes will fade. Cyprus has codified a predictable, statutory ecosystem that respects international capital while providing families with genuine Mediterranean balance, superior healthcare, and reputable private education. For the prepared principal, the non-dom framework remains one of Europe's most compelling wealth-structuring pathways.